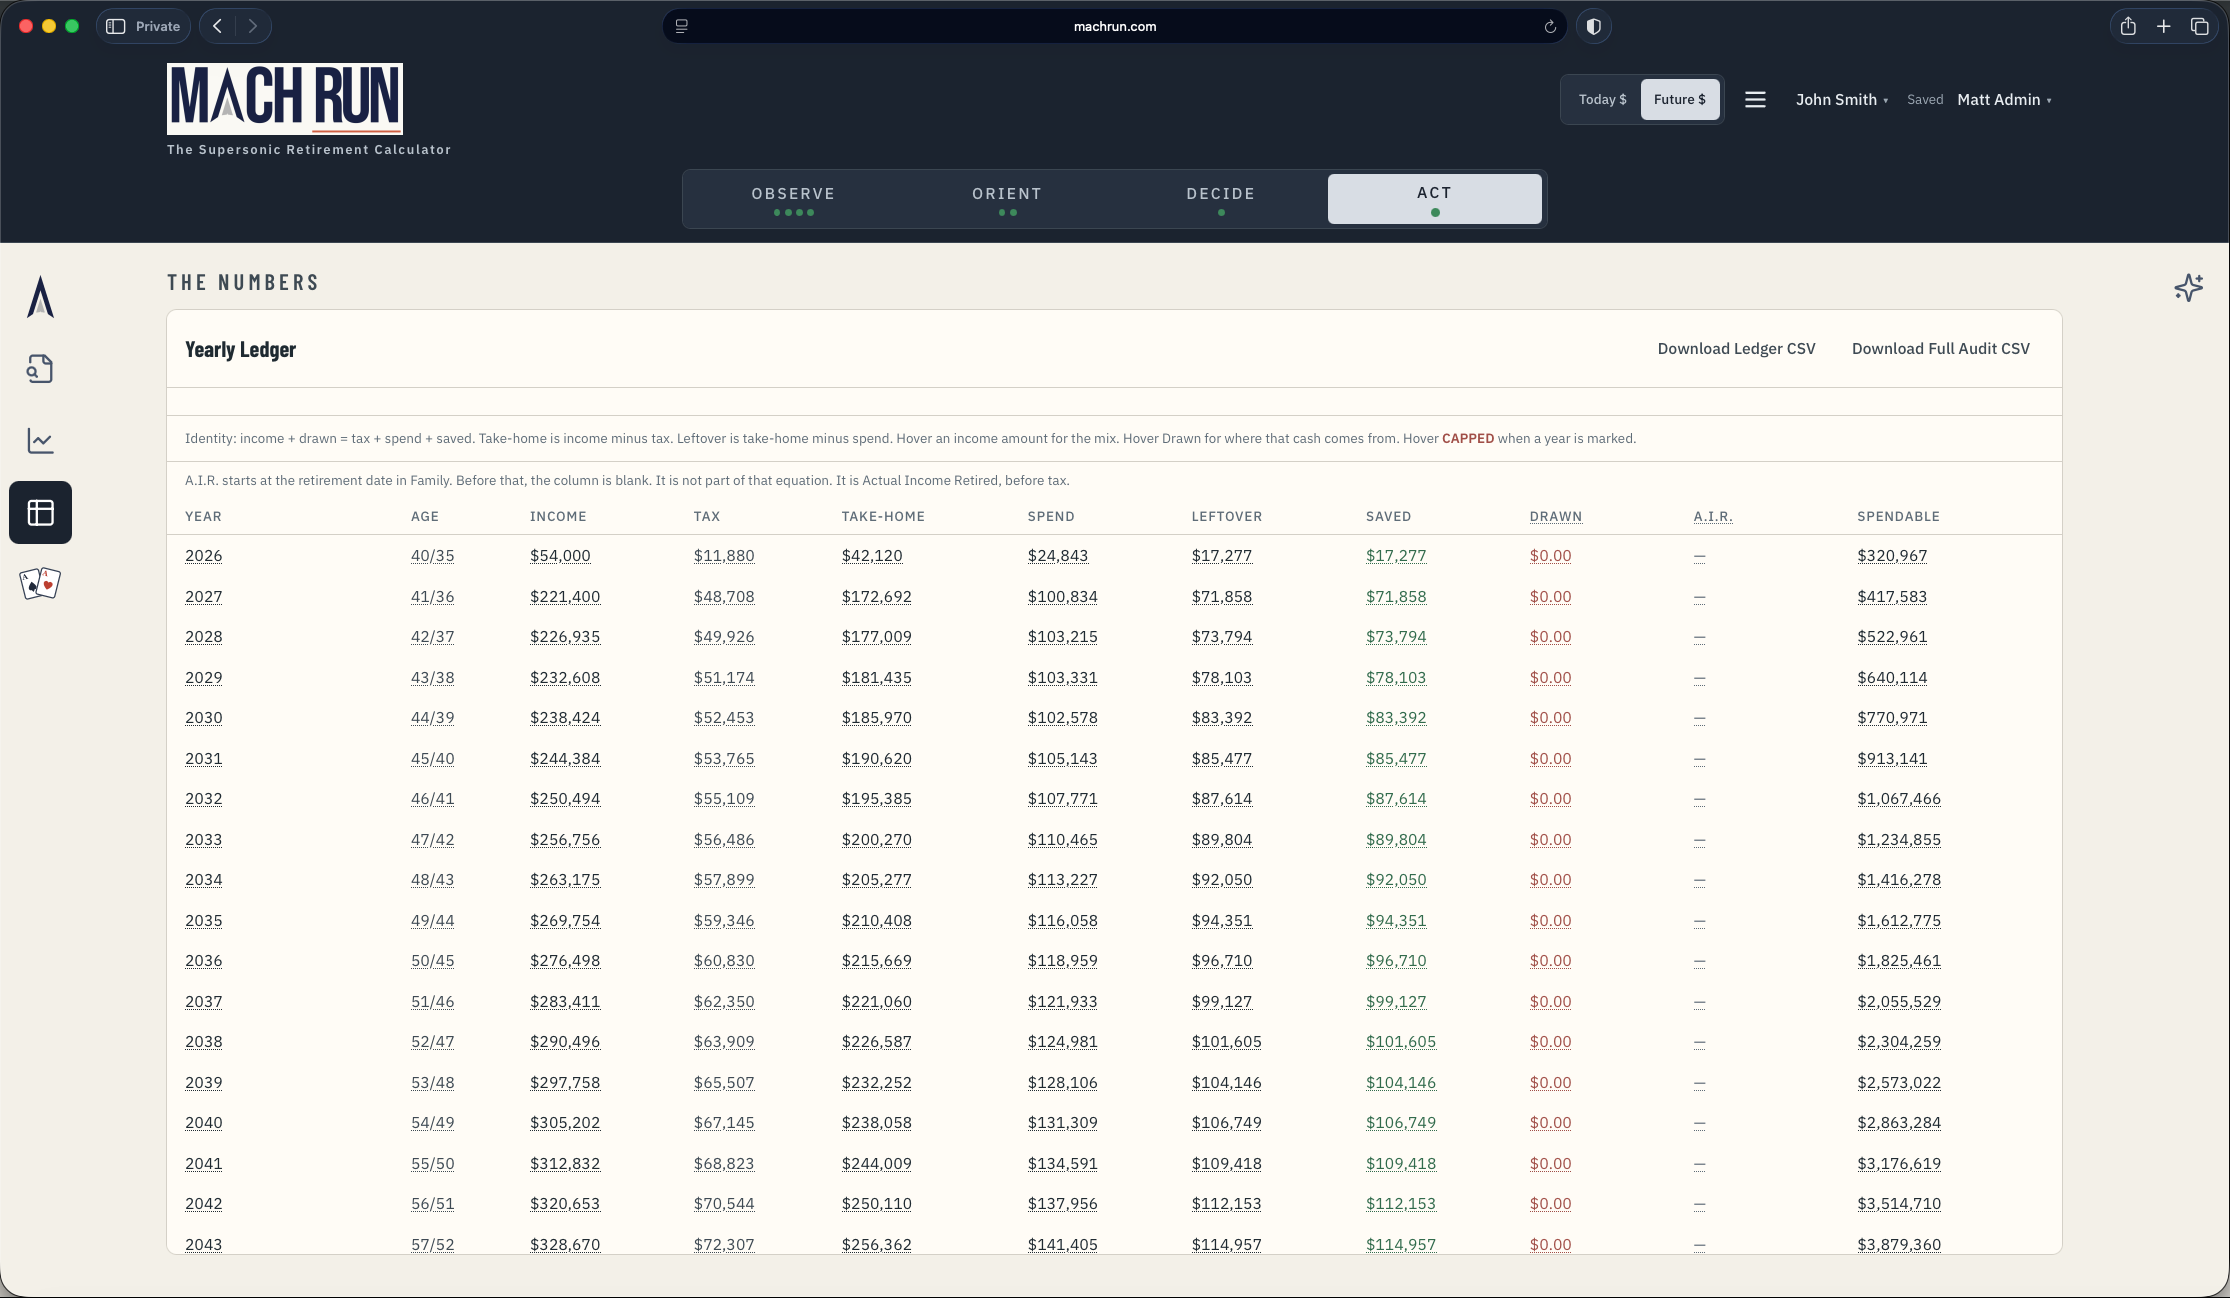
Military pay, spouse pay, retired pay, VA, and TSP. One page.
Plan for pay increases at a promotion, the yearly NDAA, and planned COLA. Change the savings rate and contributions, and watch that date and FIRE number move. Free to start — 2 incomes, 2 accounts, 2 contributions. $4 a month gets you more.
Six questions. One account. About a minute. See what it pays you each month.
Opens the Hale demo. You can change any number, or clear the demo.
Observe
Family & Assumptions
Assets & Liabilities
Act
Takeoff & Analysis
Charts, Ledgers & Monte Carlo
Engine
Orient
Income & Spending
Decide
Contributions
Observe
Family & Assumptions
Assets & Liabilities
Act
Takeoff & Analysis
Charts, Ledgers & Monte Carlo
Engine
Orient
Income & Spending
Decide
Contributions
Observe
Family & Assumptions
Assets & Liabilities
Act
Takeoff & Analysis
Charts, Ledgers & Monte Carlo
Engine
Orient
Income & Spending
Decide
Contributions
1 · The problem
Retirement is complicated.
Military retired pay, VA compensation, TSP, Social Security, spouse income, and expenses all operate on different timelines. Keeping a plan current takes a large time investment.
2 · The frustration
Most calculators only show pieces of the puzzle, and don't allow unlimited iterations.
Spreadsheets are outdated. Most popular software only tracks investments and spending, without planned income changes and COLA. But these are built into MACH RUN.
3 · The solution
One household picture, unlimited iterations.
MACH RUN brings the entire household financial picture together — a promotion, a new job, a spouse's paycheck, TSP, military retired pay, VA, and the nest-egg goal — in one place. Along with unlimited changes and iterations of your plan.
For military and veteran households
Promotions, TSP, retired pay, and VA on one strip
Pay steps up at promotion, then retired pay and VA take over, all on the same strip. MACH RUN blends that with the rest of the household and shows what the mix can pay in retirement.
Sample blend
$6,500 a month
$78,000 in the first year of this example. Your MACH RUN uses the numbers you type.
Present value of a federal annuity
$1,280,125
Military retired pay at age 50, paid through age 95. Discounted at 4% with a 2.5% COLA.
MACH RUN can also estimate what your military retired pay and VA are worth today — the present value of a federal annuity that would pay the same checks.
Present value of a federal annuity
$720,070
VA at age 50, paid through age 95. Discounted at 4% with a 2.5% COLA.
MACH RUN can also estimate what your VA compensation is worth today — the present value of a federal annuity that would pay the same checks.
TSP at required withdrawal
$442,800
Estimated Traditional TSP balance at age 75, assuming $1,500 a month withdrawal. Roth has other rules.
Military retired pay
$3,200
a month
VA
$1,800
a month
TSP withdrawal
$1,500
a month
Military retired pay and VA show the present value of a federal annuity at age 50. TSP shows the balance at the required-withdrawal age, 75.
4 · The process
Observe
Family, accounts, and the household as it stands.
Orient
Current and future income and spending — where the dollars come from, and where they go.
Decide
Contributions and the nest-egg goal, one change at a time.
Act
Run it. Read the result and act. Start the loop again at Observe.
Mouse over a step to see The Process.
Jordan is 29, an O-3 over 8. The TSP and Roth accounts are about $44,500.
Pay steps from O-3 to O-4, then to O-5 at 16 years. Military retired pay at 41 is about $4,643. Spending is $8,600 a month.
The goal is $1.8 million at 60. Five percent to the TSP, then $200 a month to the 401(k), does not reach it. MACH RUN shows $800 more a month, or retiring 5 years later covers the gap.
At 60 they have about $1.57 million. Short of $1.8 million. Save the $800, or retire at 65, and the goal is met.
5 · The outcome
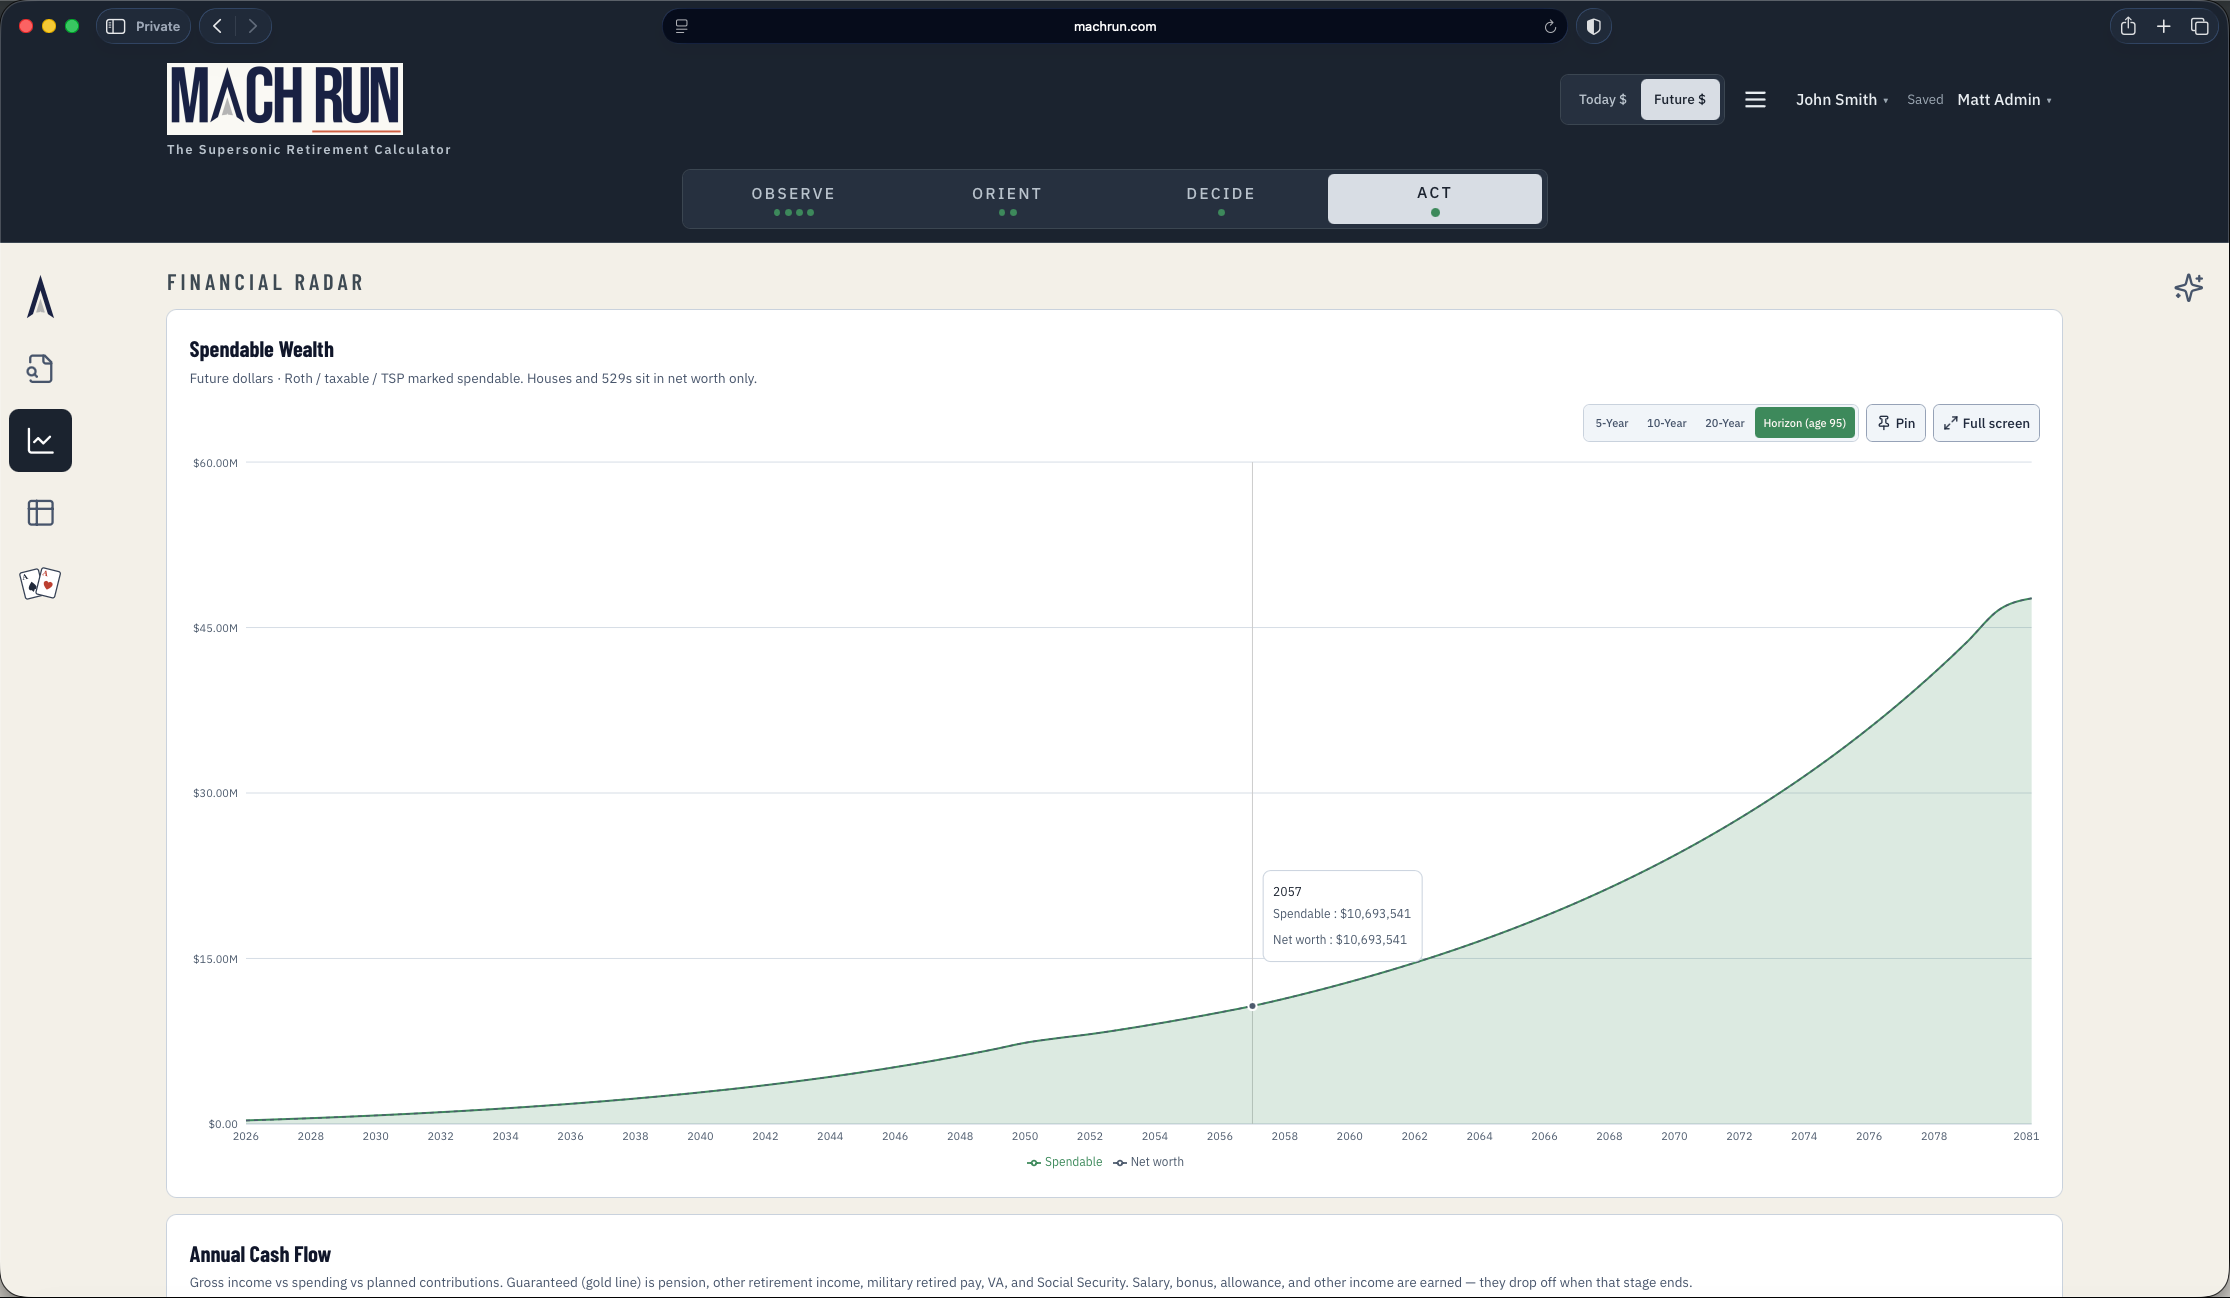
See the trajectory, then test a change.
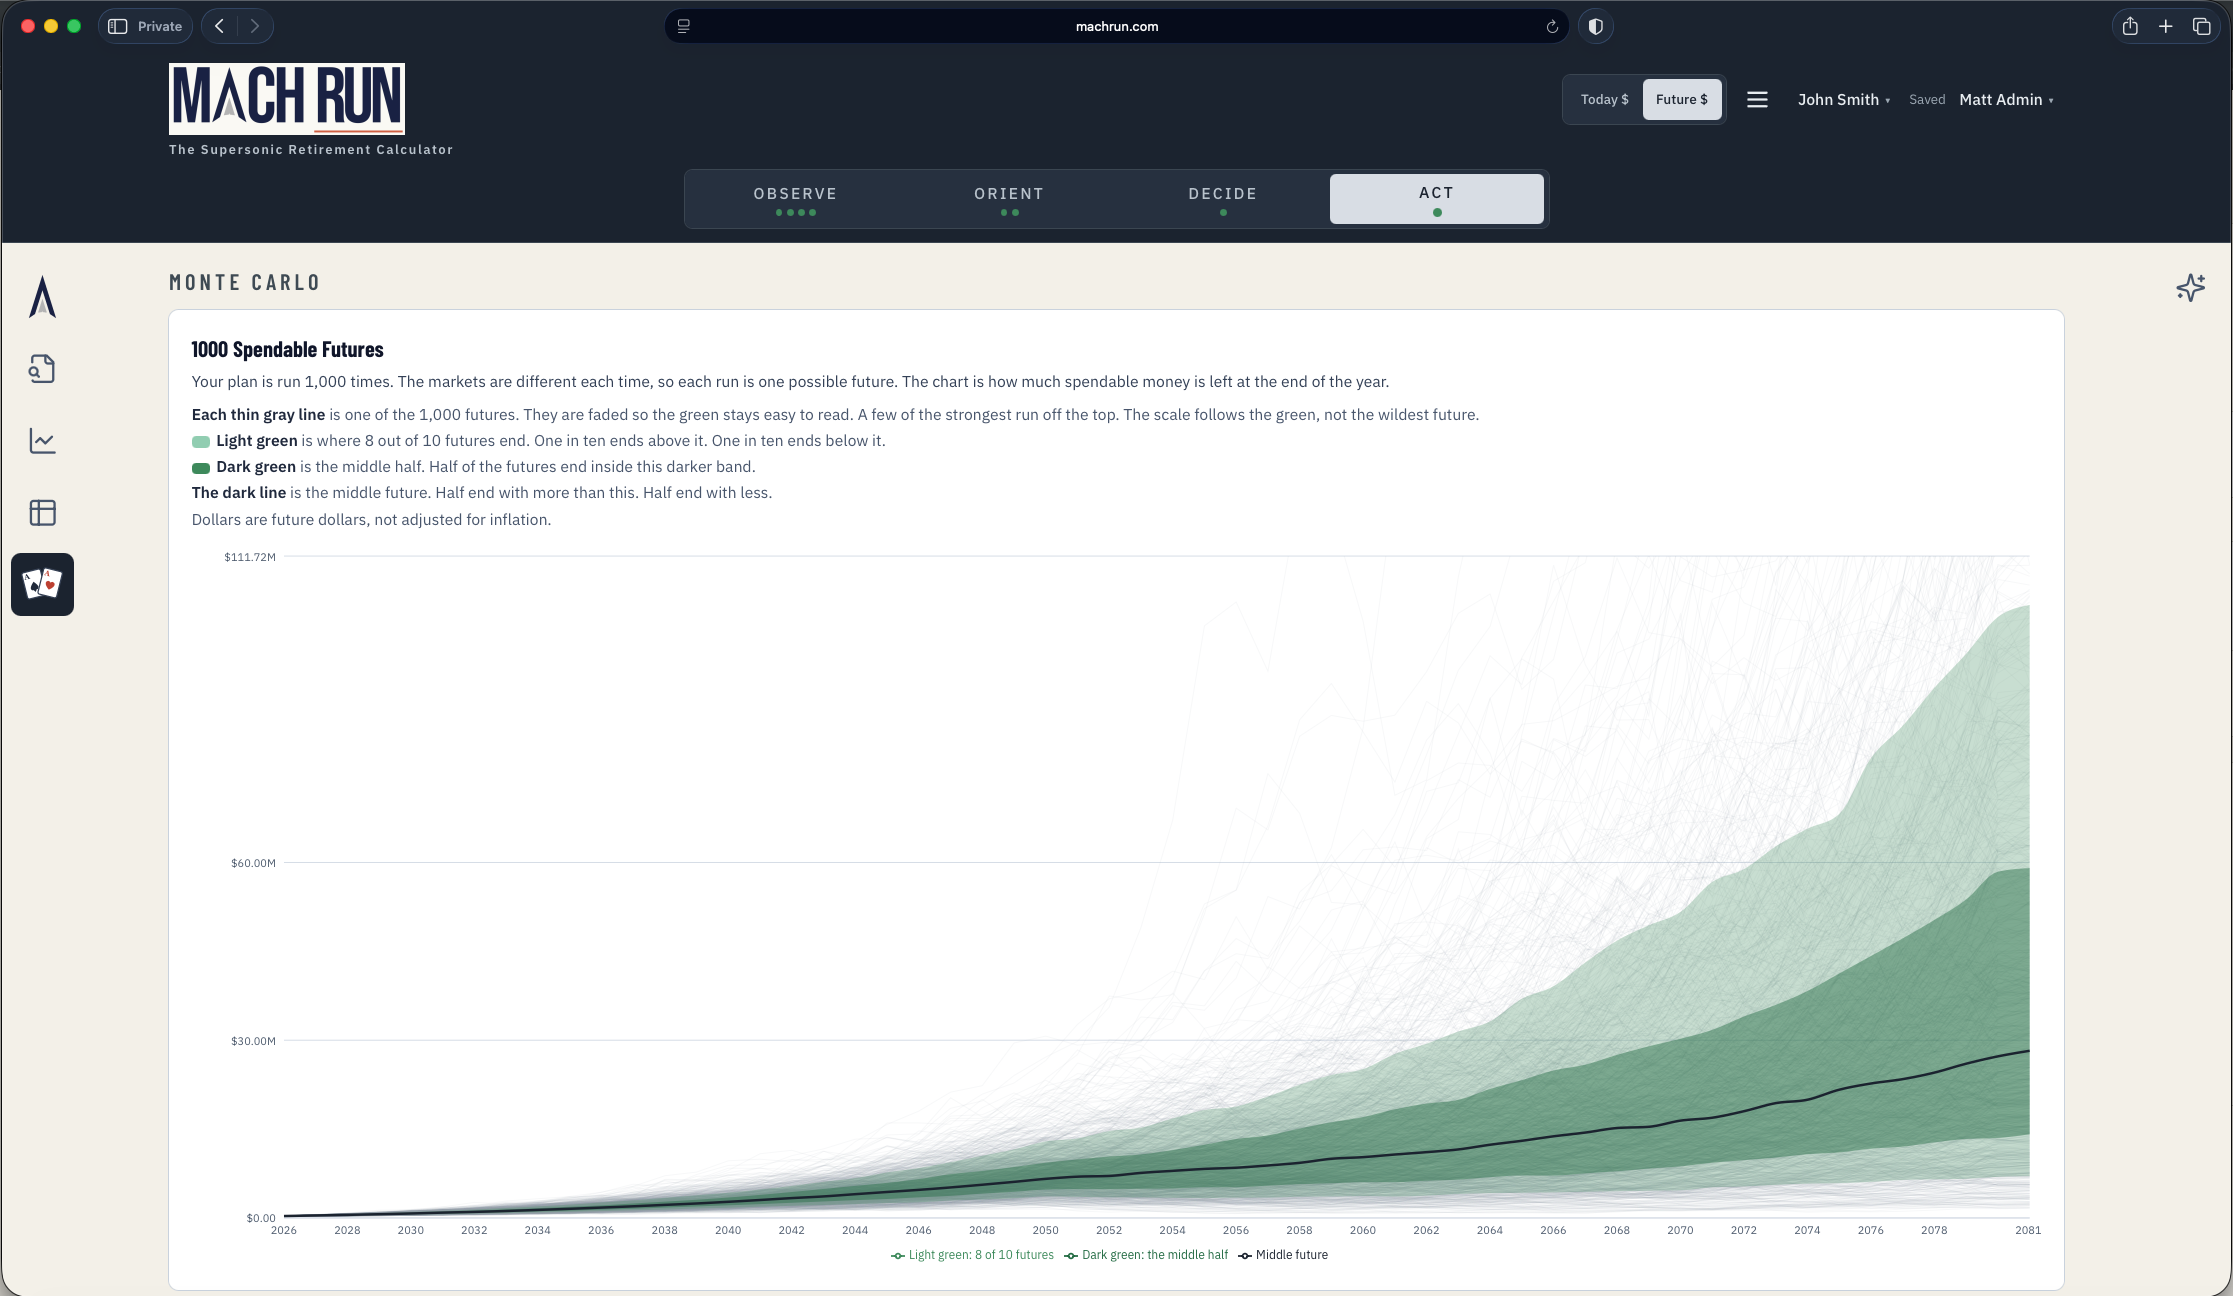
Understand where retirement is headed, see a shortfall if there is one, and try a change that could improve the position. A test across 1,000 futures available on Individual Unlimited.
The Hale Family Demo
Jordan Hale is 29 and an Air Force captain, O-3 with 8 years in. Riley Hale is 28 and teaches school. They have three children. Jordan's basic pay is $8,126 a month, plus BAH and BAS. Riley earns $4,200. He pins on O-5 at 16 years and leaves the military in June 2038, at 20 years and age 41, with about $265,000 in the TSP and Roth accounts. Retired pay is about $4,643 a month, 40% of his O-5 high-3. A second career follows. They plan to retire at 60, in June 2057. The nest-egg goal is $1.8 million in today's dollars. On this savings rate they are short of it.
Original plan
About $1.57 million at age 60, short of the $1.8 million goal.
Higher savings rate
Save about $800 more a month, starting now. Same retirement age, and the goal is met with room to spare.
Delay retirement 5 years
Same savings rate. Five more working years, and the goal is met.
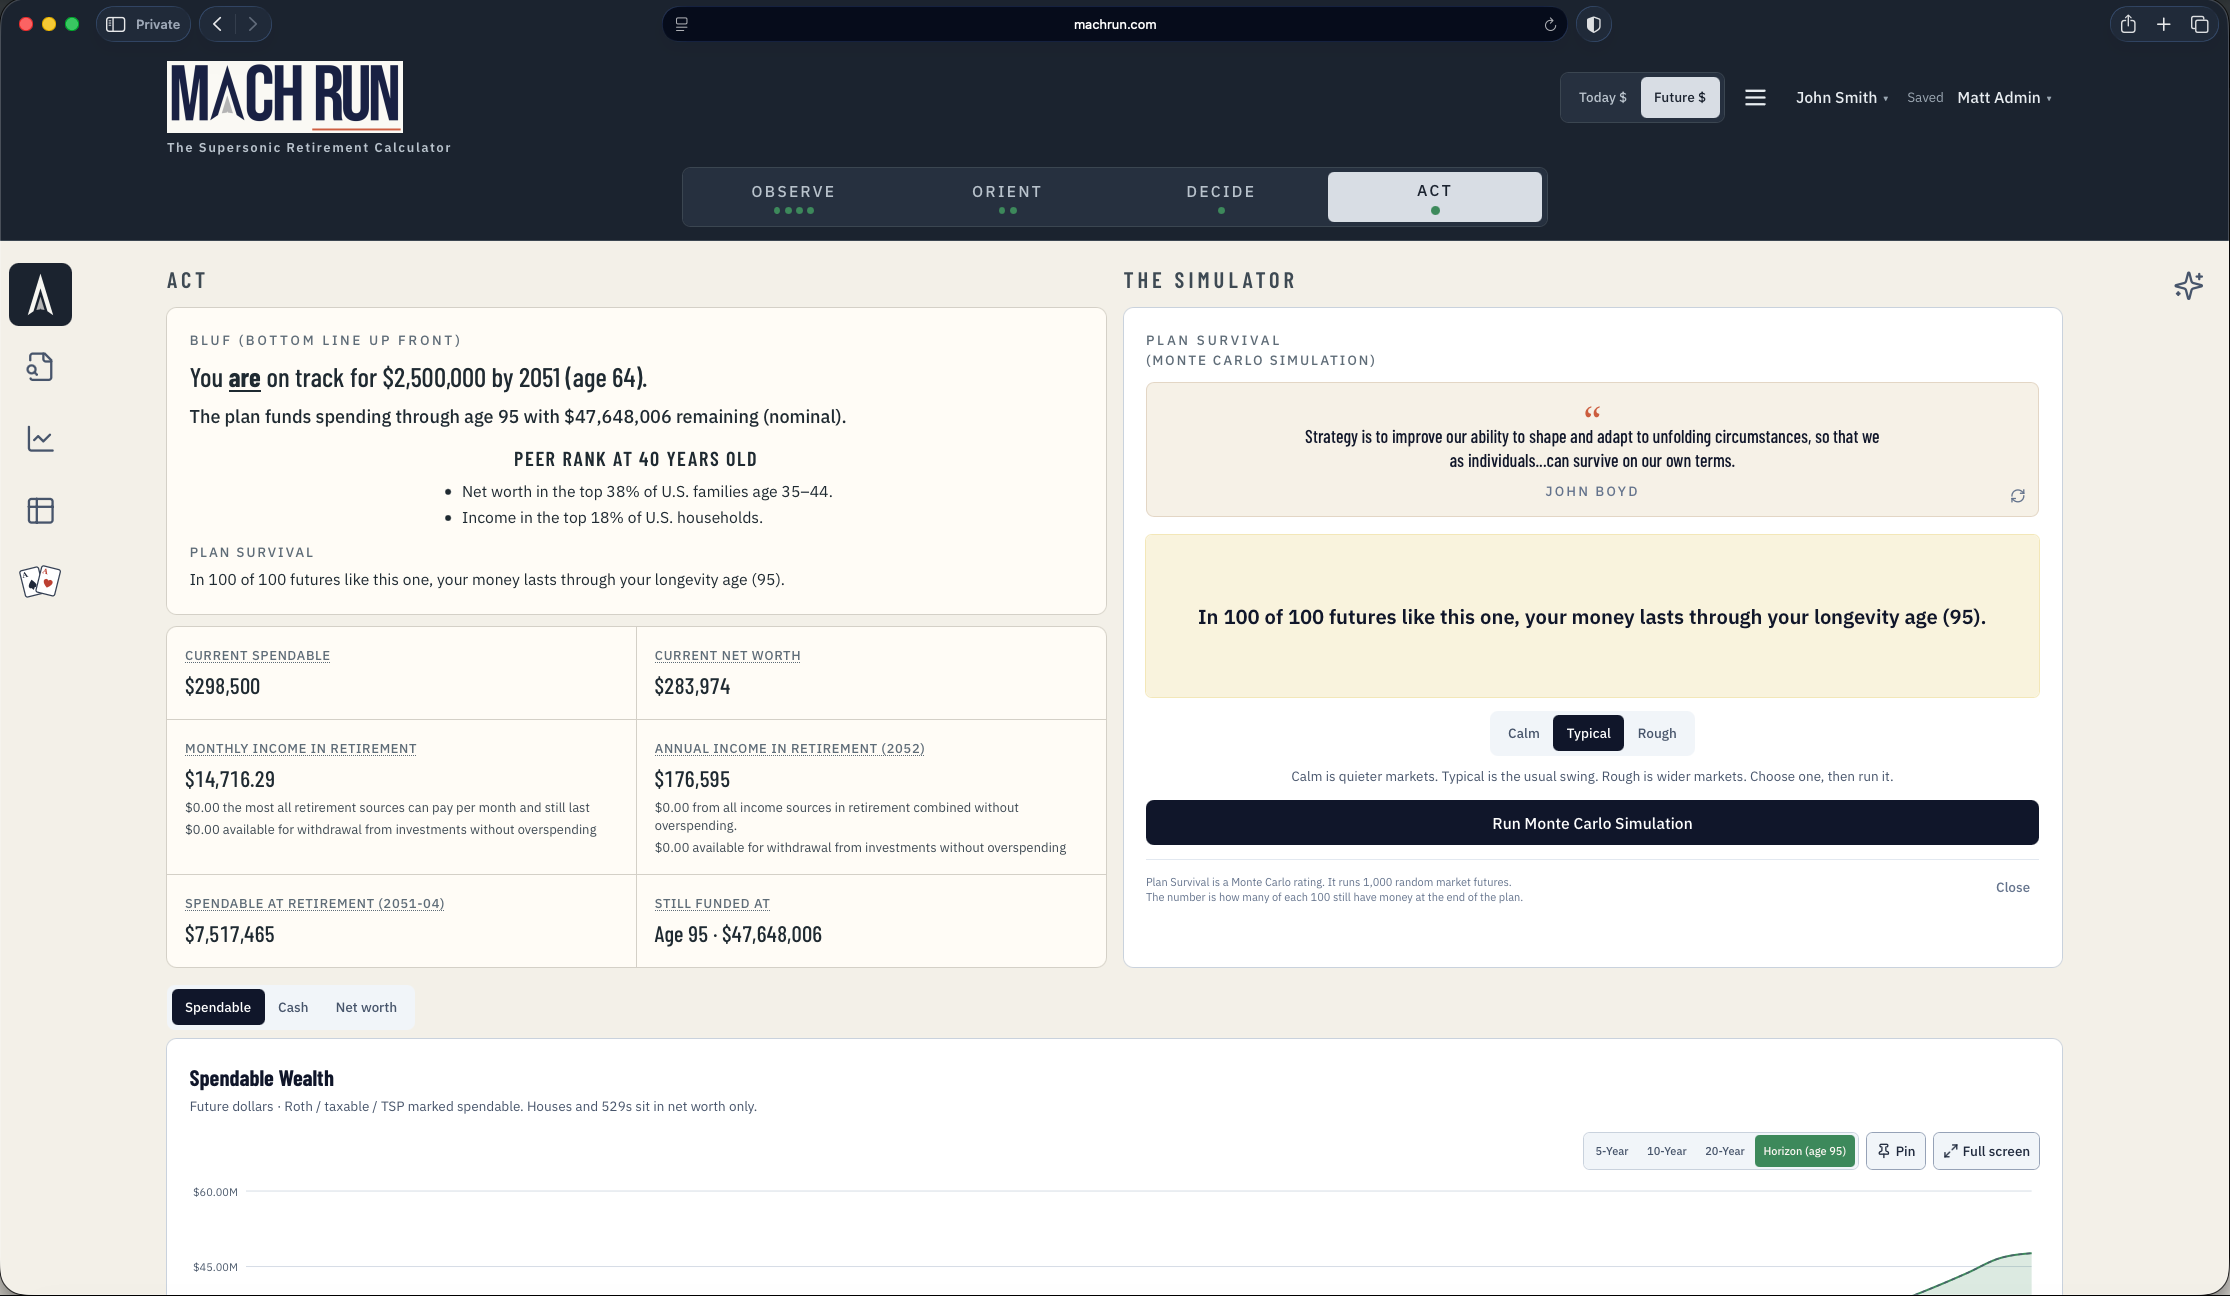
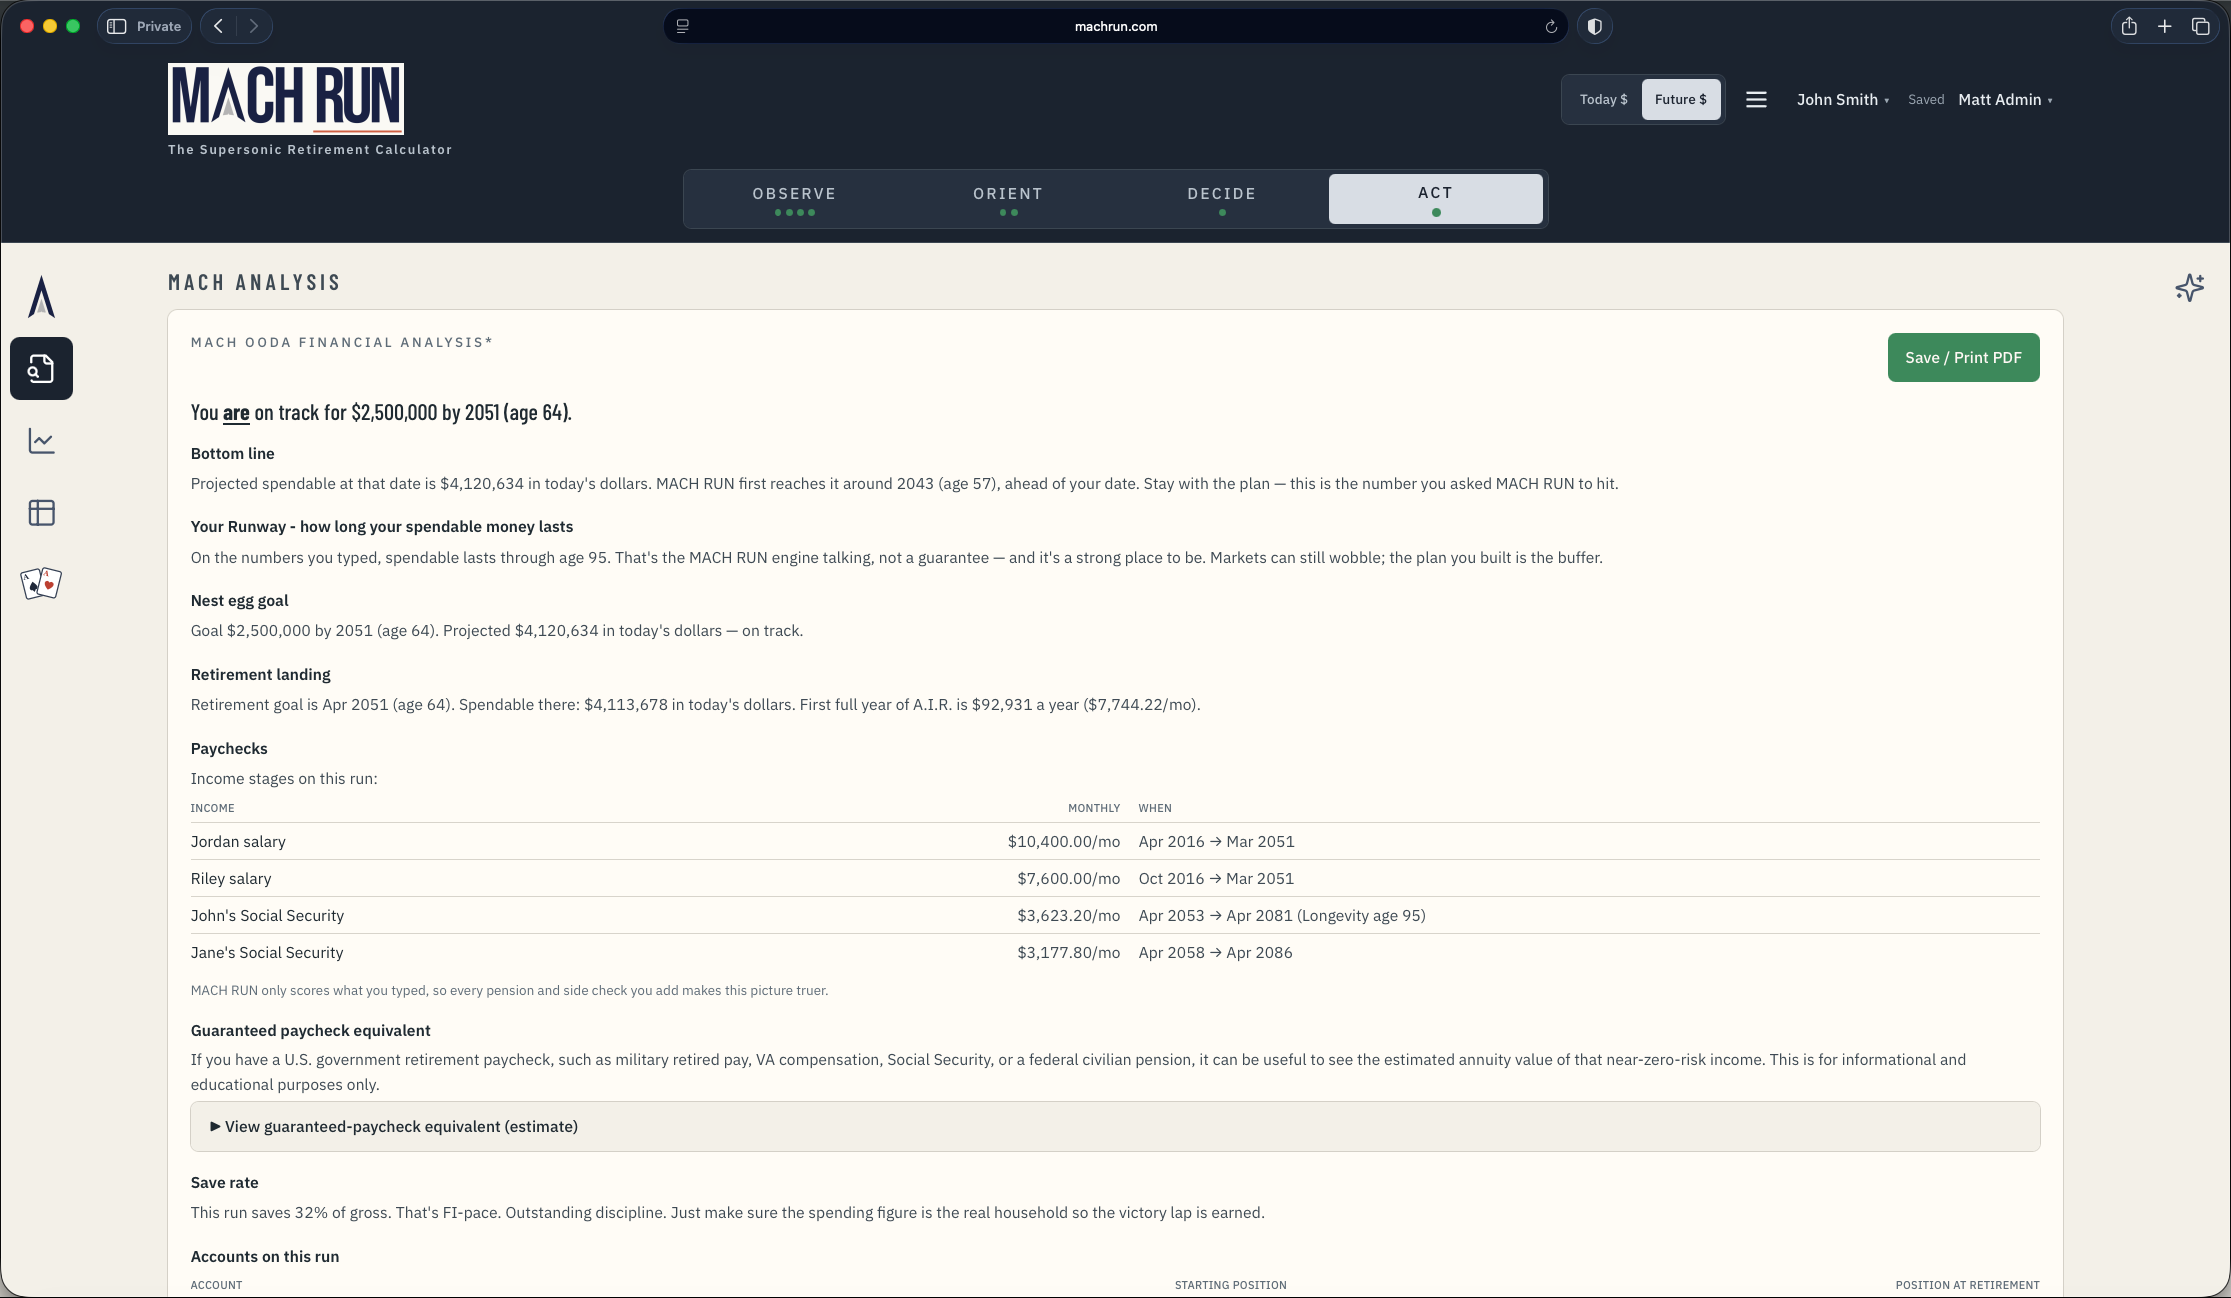
BLUF (Bottom Line Up Front)
At 60 the Hales have about $1.57 million, short of the $1.8 million goal.
The TSP and Roth accounts are about $265,000 when Jordan leaves as an O-5 at 41. Retired pay is about $4,643 a month. Growth from there to 60 is modest on this savings rate.
Sample, from the pre-filled Hale demo. Not your plan.
BLUF (Bottom Line Up Front)
Saving about $800 more a month, starting now, leaves about $2.1 million at 60.
Same retirement date, June 2057. The $800 comes out of spending. It goes into the Roth TSP while he is in uniform, then into the second-career 401(k). New TSP contributions stop at military retirement. The balance keeps compounding. In today's dollars it adds about $530,000.
Sample, from the pre-filled Hale demo. Not your plan.
BLUF (Bottom Line Up Front)
Retiring at 65 instead of 60 meets the $1.8 million goal.
Same savings rate. Five more working years. About $1.9 million in today's dollars.
Sample, from the pre-filled Hale demo. Not your plan.
Households that plan for retirement end up with roughly three times the wealth of those that don't.1
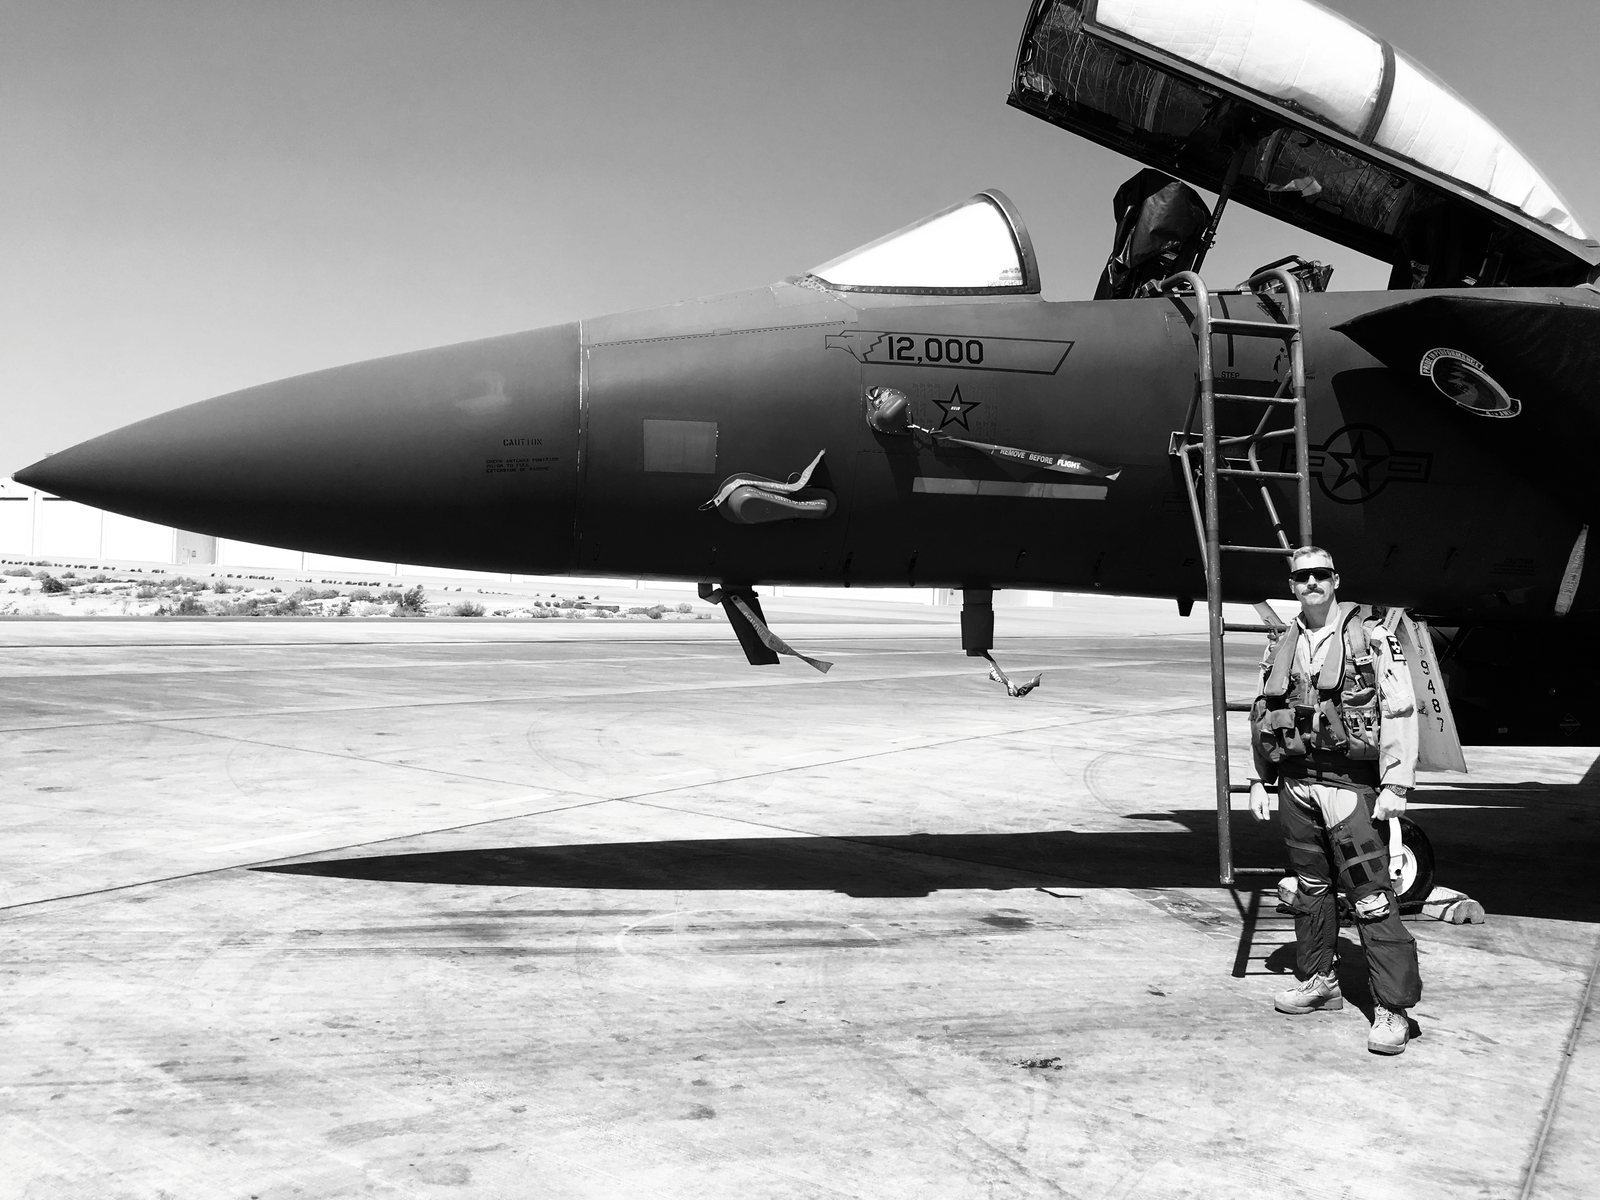
Matthew "Cain" Olde flew F-15s for the U.S. Air Force and retired into the same problem every military household has: active duty, guard/reserve, or retired pay, VA, TSP, a spouse's paycheck, and Social Security all land in different places, and nothing shows them together. His father was a USAF fighter pilot who became a Certified Financial Planner, so he grew up with a love of fighter jets and personal finances. MACH RUN is the tool Matt wished existed, built after he hung up the G-suit.
“Decision making is the bridge between understanding the world and changing it through action.”
- John Boyd
Observe
Family
Who is this plan for?
Start with you. Add a spouse or a child if they belong here.
Your name
Your birthday
Observe
Assumptions
What should this plan assume?
Returns, COLA, inflation, tax, and where a surplus goes.
Nominal return, percent a yearReal, about 4.39%
Nominal return in retirement, percent a yearReal, about 2.44%
Nominal COLA, percent a year
Inflation, percent a year
COLA is the default for every income. It steps up each January and stays flat the rest of the year. Set a different COLA on an income in Orient.
Ordinary tax rate, percent
Sweep surplus into
Observe
Assets
What accounts do you have?
Spendable (retirement) $0.00 · Net worth $0.00. These accounts are the only ones ORIENT can sweep into and DECIDE can contribute to. Per-account return blank uses the global 7% nominal (you set the global % in OBSERVE - Family).
Observe
Liabilities
What do you owe?
Car, student, HELOC, personal, credit card. Debt reduces net worth. House mortgages stay nested within the real estate asset accounts — do not also enter those here.
Orient
Income
What income is coming in?
Each block is one paycheck over a specific stretch of time. Name it, set the monthly amount, set start and end. MACH RUN assumes you are paid at the end of the month. If end date is left blank, it assumes monthly income paid until primary age death set in OBSERVE - Family.
Orient
Spending
What does the household spend?
Spending phases are in today's dollars and inflate with the assumption rate set in OBSERVE - Family. Overlapping phases add together, so ensure one a spending phase starts after the previous one ends. Add a second phase when spending steps up or down and only overlap when that is intentional.
Decide
Goals
What are you aiming for?
Balances peg to the as-of date. Blank end dates run through the longevity age. Act’s Spendable strip keys off the retirement date. Pick a nest egg or a monthly paycheck. Pension, VA, military retired pay, and Social Security in this run count toward the paycheck. A blank goal is not scored.
As-of date
November 12, 2026
Project through longevity age
Retirement goal date
Nest egg goal (today $)
$
Decide
Contributions
What goes into the accounts?
Regardless what you set for investment amounts, MACH RUN only allows you to invest available dollars after income minus taxes and spending — it will not invent extra cash — so ensure your income and spending is accurate.
If your 401(k) or TSP has a company match, select that below. That match is bonus money -- it is not deducted from your paycheck.
Tax-qualified accounts are funded first when the paycheck cannot cover every contribution.
Add an account in Observe first — then this button will attach a rule to it.